
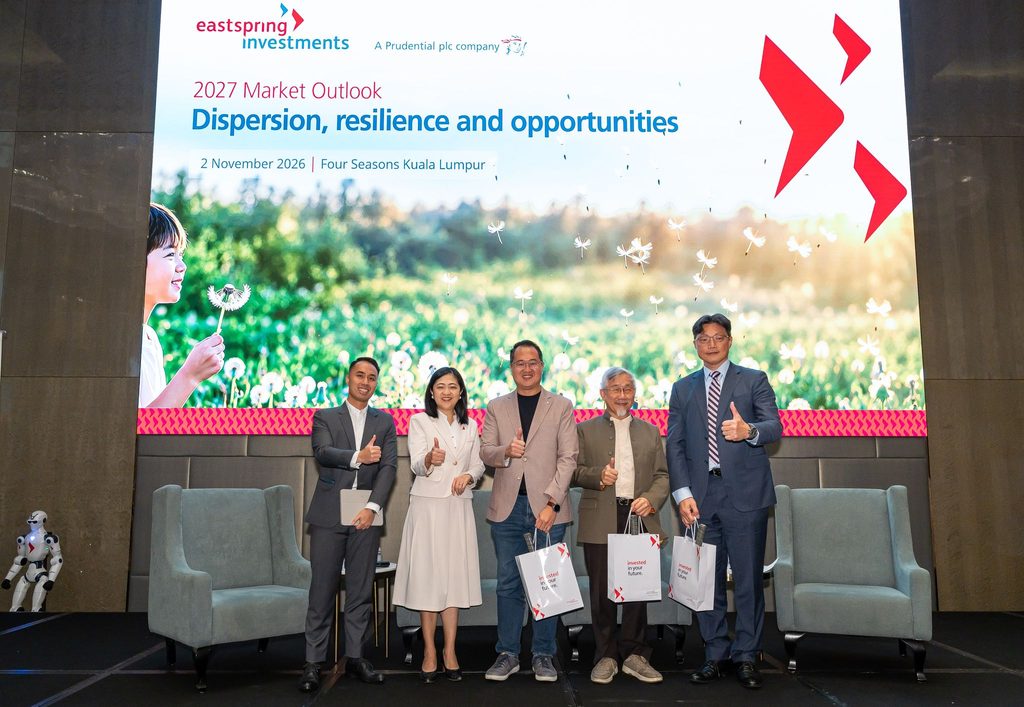
This was the trillion-dollar question posed at a panel I joined on November 2, 2026.
Around 170 clients, partners, and industry leaders gathered at the Four Seasons Hotel for the annual flagship event hosted by Eastspring Investments, the Asian asset management arm of Prudential plc managing over US$290B across 10 Asian markets.
The discussion zeroed in on Asia’s AI Engine – the ecosystem supplying 70% of the world’s chips:
✅ 92% of advanced sub-7nm chips are fabricated in Taiwan.
✅ Over 90% of high-bandwidth memory (HBM) originates from South Korea (with SK Hynix commanding ~50%).
✅ Closer to home, Malaysia already packages, tests, and ships 13% of global chips, with national ambitions to move up the value chain into IC design and advanced packaging.
Yet today’s elevated expectations raise a sobering question:
Are AI valuations overheated, unrealistic, or unsustainable?
As Eastspring’s Chief Investment Officer Vis Nayar pointed out, global data centers will demand 75–110 GW of power by 2030, requiring US$2.9T to US$4.2T in capex – much of it debt-fueled.
Can commercial adoption consume all that compute fast enough to justify this capital spending? What happens to the Asian supply chain if the music stops?
Tough one.
~~
From an investor’s view, borrowing at 5% to chase a projected 30% return on data center infrastructure seems too good to pass up.
For Asia’s factory owners and supply chain providers, the equation is fundamentally different. They cannot – and do not – gamble balance sheets on wishful thinking:
▶️ Technology must be acquired, licensed, or developed in-house.
▶️ Talent must be recruited, trained, and honed.
▶️ Operations must achieve zero-defect yields and peak reliability before winning a single purchase order.
There is zero margin for error.
Incumbents in Taiwan and Korea are not slowing down, and catching up demands serious capital.
The question isn’t whether you can afford to enter this race. It’s whether you can afford NOT to be in it.
The silver lining – as I emphasised on the panel – is that the CORE CAPABILITIES required to compete in AI transcends beyond AI.
Mastering sub-micron fine-pitch advanced packaging, ultra-precision tooling, thermal dissipation materials, and complex high-speed test methodologies isn’t exclusive to AI hardware.
They are the exact same building blocks required for next-generation smart devices, humanoid robotics, edge compute, and automotive controllers.
When you have the CORE CAPABILITIES, the market will beat a path to your door.
A great way to invest – if you know what to build.
And do not depend on projections provided by valuation-driven companies.
Thank you to fellow panelists Teng Chow Ooi, Eric Y.P. Lin, CFA, and moderator Eu-Roy Lai, CFA for a stimulating discussion.

